
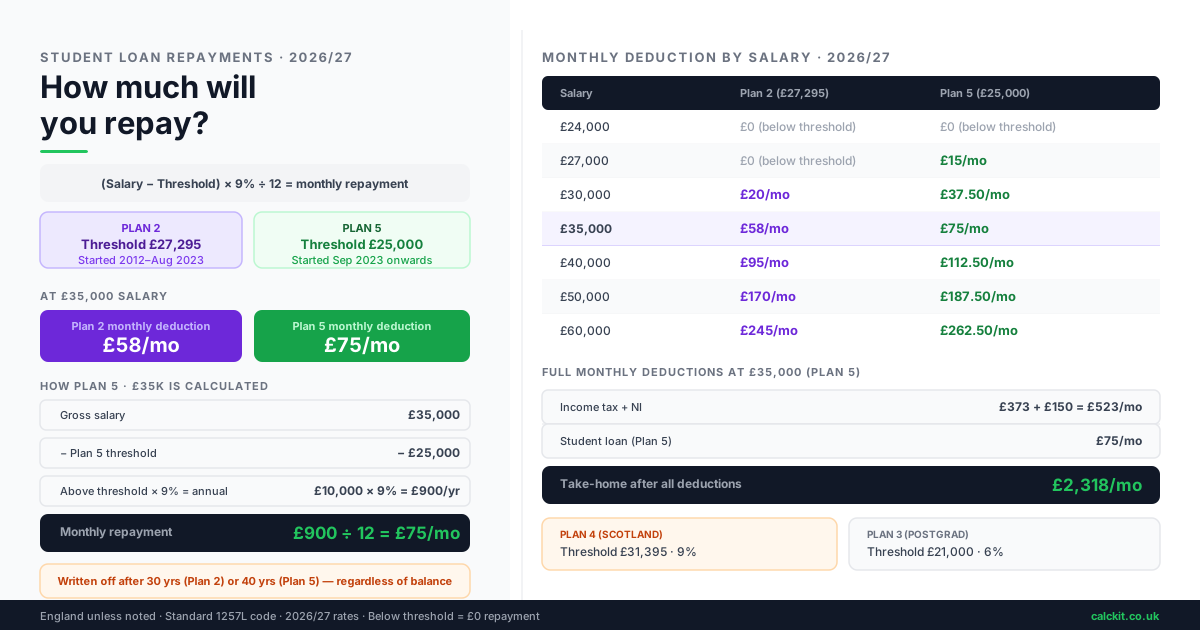
Student loan repayments are not calculated on your whole salary — only on the portion above your plan's threshold, at a flat 9%. This makes the monthly cost much lower than most graduates expect when they first see the total debt on their account. On a £35,000 salary, the deduction is £75 a month on Plan 5, or £58 a month on Plan 2.
💷Which plan are you on?
Your plan is determined by when and where you studied:
| Plan | Who it applies to | Threshold | Rate | Write-off |
|---|---|---|---|---|
| Plan 2 | England/Wales, started 2012–Aug 2023 | £27,295 | 9% | 30 years |
| Plan 5 | England, started Sep 2023 onwards | £25,000 | 9% | 40 years |
| Plan 4 | Scotland (any start date) | £31,395 | 9% | 30 years |
| Plan 3 | Postgraduate loan (all UK) | £21,000 | 6% | 30 years |
If you are unsure which plan you are on, check your student loan statement on the Student Loan Company portal or look at your most recent P60 — the loan plan is listed separately from PAYE deductions.
The repayment formula
Monthly repayment = (annual salary − threshold) × 9% ÷ 12
If your salary is below the threshold, you repay nothing — not even interest accumulates in a way that affects what you eventually pay (Plan 5 interest is RPI only; Plan 2 adds up to 3% above RPI while your balance grows, but repayments are still never triggered below the threshold).
Plan 2 monthly repayments (threshold £27,295)
| Salary | Above threshold | Annual | Monthly |
|---|---|---|---|
| £27,295 | £0 | £0 | £0 |
| £28,000 | £705 | £63.45 | £5 |
| £30,000 | £2,705 | £243.45 | £20 |
| £32,000 | £4,705 | £423.45 | £35 |
| £35,000 | £7,705 | £693.45 | £58 |
| £40,000 | £12,705 | £1,143.45 | £95 |
| £45,000 | £17,705 | £1,593.45 | £133 |
| £50,000 | £22,705 | £2,043.45 | £170 |
| £60,000 | £32,705 | £2,943.45 | £245 |
Plan 5 monthly repayments (threshold £25,000)
| Salary | Above threshold | Annual | Monthly |
|---|---|---|---|
| £25,000 | £0 | £0 | £0 |
| £27,000 | £2,000 | £180 | £15 |
| £30,000 | £5,000 | £450 | £37.50 |
| £32,000 | £7,000 | £630 | £52.50 |
| £35,000 | £10,000 | £900 | £75 |
| £40,000 | £15,000 | £1,350 | £112.50 |
| £45,000 | £20,000 | £1,800 | £150 |
| £50,000 | £25,000 | £2,250 | £187.50 |
| £60,000 | £35,000 | £3,150 | £262.50 |
Plan 2 vs Plan 5 — side by side
At the same salary, Plan 5 costs more each month because the threshold is £2,295 lower:
| Salary | Plan 2/month | Plan 5/month | Plan 5 extra |
|---|---|---|---|
| £30,000 | £20 | £37.50 | +£17.50 |
| £35,000 | £58 | £75 | +£17 |
| £40,000 | £95 | £112.50 | +£17.50 |
| £50,000 | £170 | £187.50 | +£17.50 |
The difference stays roughly constant at £17.50/month across salary levels — that is simply £2,295 × 9% ÷ 12 = £17.21. The gap narrows at lower salaries when Plan 2 earners are still below their threshold and Plan 5 earners are already repaying.
Plan 4 (Scotland) and Plan 3 (postgraduate)
Plan 4 (Scotland, threshold £31,395): Scottish graduates start repaying at a higher income than English graduates — roughly £4,100 more than Plan 5. At £35,000, a Plan 4 borrower pays 9% of £3,605 = £324/year, or £27/month. At £40,000: 9% of £8,605 = £65/month.
Plan 3 (postgraduate, threshold £21,000, rate 6%): Postgraduate loan repayments run simultaneously with undergraduate repayments, not instead of them. The rate is 6% rather than 9%.
| Salary | Plan 3 monthly | Plan 3 + Plan 5 combined |
|---|---|---|
| £25,000 | £20 | £20 |
| £30,000 | £45 | £82.50 |
| £35,000 | £70 | £145 |
| £40,000 | £95 | £207.50 |
Full monthly deductions at £35,000
Seeing the student loan in context of your full PAYE deductions:
| Deduction | Plan 5 | Plan 2 |
|---|---|---|
| Income tax | £373 | £373 |
| National Insurance | £150 | £150 |
| Student loan | £75 | £58 |
| Total deductions | £598/mo | £581/mo |
| Take-home | £2,318/mo | £2,335/mo |
Based on 2026/27 rates, standard 1257L tax code, no pension contributions.
Does repaying early make sense?
For most borrowers, no. Because:
- Repayments stop automatically if income drops below the threshold
- The debt is written off after 30 or 40 years regardless of the remaining balance
- Research suggests fewer than 20% of Plan 2 graduates clear their balance before write-off
The only scenario where early repayment makes financial sense is if you are certain you will earn well above the threshold for the full write-off period — clearing the debt before it is written off anyway. For the majority of graduates, voluntary lump-sum payments go toward a debt that would otherwise have been cancelled, so the money is simply lost.
The student finance guide covers the early repayment question in full, including the Plan 2 vs Plan 5 interest rate comparison.
Frequently Asked Questions
What if I work part-time or take a career break?
Repayments are based on your actual earnings in each pay period. If you go part-time and earn below the threshold, you pay nothing — no catch-up payments are required when you return to full-time work. The write-off clock continues regardless of whether you are actively repaying.
Will my employer know I have a student loan?
Yes. PAYE records include which student loan plan you are on, and the deduction appears on your payslip. This is not sensitive information from an employment perspective — it is treated the same as any other PAYE deduction. Lenders may ask about student loan repayments on mortgage applications, since the monthly cost reduces your disposable income.
Last updated November 2026. Plan 2 threshold £27,295; Plan 5 threshold £25,000; Plan 4 threshold £31,395; Plan 3 threshold £21,000. All figures are gross/PAYE-based for England unless otherwise noted. Scottish Income Tax rules apply to Scottish Plan 4 borrowers — see the Scottish income tax guide.